Here’s a number that surprises a lot of buyers: in October, Virginia Beach sellers of detached homes got about 96.9% of their original list price. That means homes were selling for about 3% under asking.
Most buyers hear that and think one thing: “Great, I’ll ask for a lower price.” That can work. But in today’s market, there may be a smarter way to use the same money.
Same check, different superpower
When a seller agrees to give you something, the dollars can go to a lower price, or they can go toward your closing costs or a rate buydown. A buydown uses money paid at closing to lower your interest rate, either permanently or for the first few years.
A common version is the 2-1 buydown: your rate is 2 points lower in year one, 1 point lower in year two, and then goes to the full rate from year three on.
What it looks like on a median Virginia Beach home
Take the October median for a detached home in Virginia Beach: $470,000,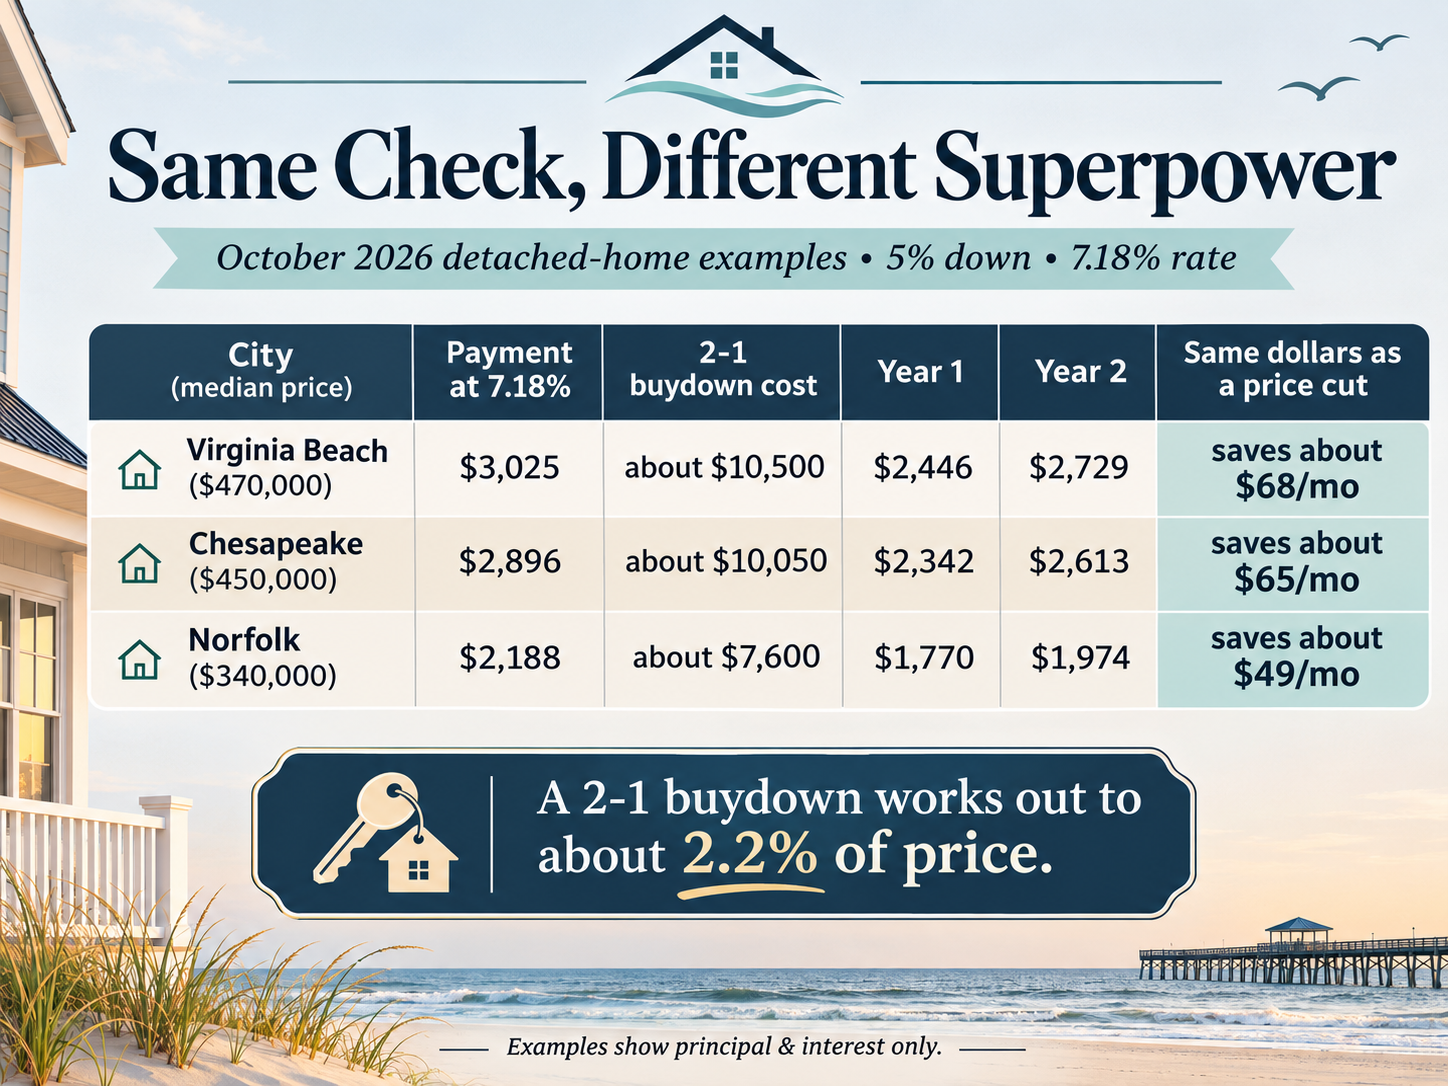 with 5% down, at this week’s average rate of 7.18%.
- Monthly principal and interest at the full rate: about $3,025
- A 2-1 buydown costs about $10,500, roughly 2.2% of the price
- With the buydown, year one: about $2,446 a month, or $579 less
- Year two: about $2,729 a month
- Year three on: back to about $3,025
Now compare that to taking the same $10,500 as a price cut. It lowers your payment by only about $68 a month.
City by city
Here’s the same comparison on the October median detached home in each city. Each 2-1 buydown works out to about 2.2% of the price.
| City (median price) | Payment at 7.18% | 2-1 buydown cost | Year 1 | Year 2 | Same dollars as a price cut |
|---|---|---|---|---|---|
| Virginia Beach ($470,000) | $3,025 | about $10,500 | $2,446 | $2,729 | saves about $68/mo |
| Chesapeake ($450,000) | $2,896 | about $10,050 | $2,342 | $2,613 | saves about $65/mo |
| Norfolk ($340,000) | $2,188 | about $7,600 | $1,770 | $1,974 | saves about $49/mo |
So which is better?
It depends on your budget and your plans.
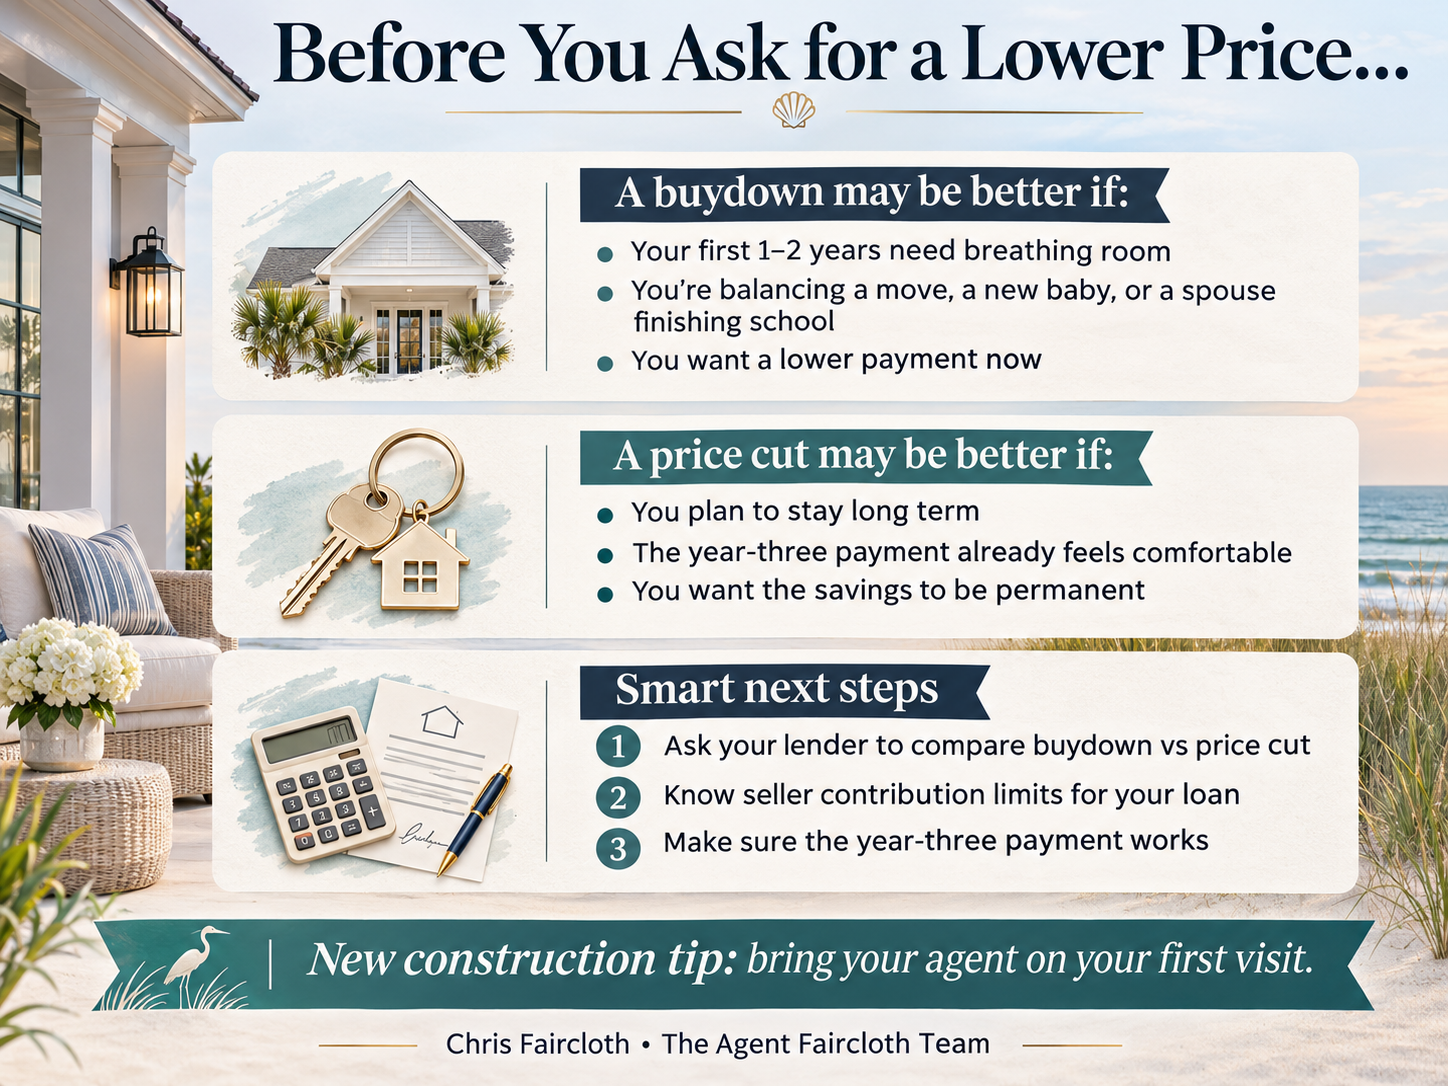
- A buydown is the bigger win if your budget is tight in the first couple of years: a new baby, a spouse finishing a degree, a move-up purchase while you wait for your old house to sell.
- A price cut is permanent and lowers what you borrow. It can make more sense if you plan to stay a long time and the year-three payment is already comfortable.
- Either way, budget for the year-three payment. A buydown is a head start, not a permanent rate. Make sure the full payment works for you before you count on it.
And if rates drop in the next couple of years and you refinance, part of what you’d gain from a permanent price cut or buydown may change. Your lender can walk you through those scenarios.
A few things to know before you ask
- There are limits. Loan programs cap how much a seller can contribute toward your costs, and the limits differ for conventional, FHA and VA loans. Your lender will confirm what applies to you.
- Talk to your lender first. Ask them to price out a buydown versus a price reduction on the actual home you’re considering.
- Let your agent structure the ask. How the request is written into your offer matters, and sellers respond differently to “lower your price” than to “help with my closing costs.”
Looking at new construction?
Builders often advertise buydowns and rate incentives too. One important tip: never visit a new construction site on your own for your first visit. If you register yourself at the model home, some builders will refuse to work with or pay your buyer’s agent. Bring your agent the first time, or call me before you go.
Want to run the numbers on a home you’re watching?
Book a 30-minute call with me and we’ll look at the price, the payment and what to ask for, side by side.
Christine “Chris” Faircloth, The Agent Faircloth Team at Swell Realty Co. | 757.288.0983
General information only, not lending advice. Examples use Freddie Mac’s national 30-year fixed average of 7.18% for the week of Nov. 5, 2026, which is not a loan offer or rate quote. All examples assume a purchase at the city’s October 2026 median detached price with 5% down and a 30-year fixed loan, and show principal and interest only. Taxes, homeowners insurance and mortgage insurance are not included, so actual payments will be higher. APR, buydown availability, cost and seller contribution limits vary by lender, loan program and borrower. Talk with a licensed lender before making any decision.
Sources
- October 2026 detached medians and 96.9% of list received: REIN MLS (Domus) data via Hampton Roads Real Estate Ramblings
- Rate: Freddie Mac PMMS, Nov. 5, 2026
- Payment and buydown figures: our calculations from the figures above